Back
Scroll to top

Homeownership Articles

Make a house your home with helpful homebuying tips.

Learn About Homeownership

Before your start your search, read these articles to understand the cost of buying a home and how mortgages work, calculate how much you can afford, budget for a mortgage and home repair costs, and more.

All Budgeting and Goals Credit: Score and More Family Finances Fending Off Fraud Paying Off Debt Personal Finance 101 Homeownership Retirement Planning for High Education Student Loans
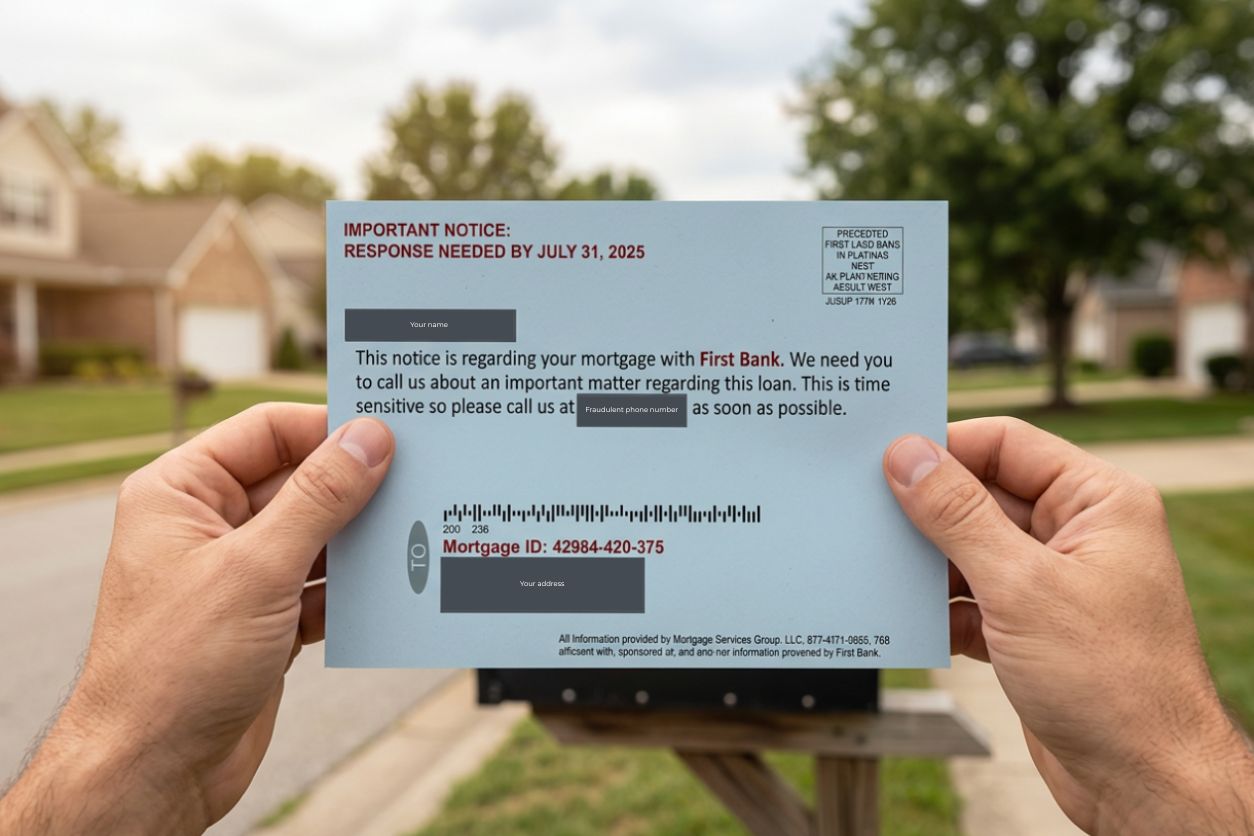
Image for tile. Received a Mortgage Postcard in the Mail? Here’s What to Know What do these postcards look like? While designs may vary, recent postcards reported by customers have included: A reference to a mortgage with First Bank Language suggesting an urgent response is needed A phone number to call regarding a loan matter A “Mortgage ID” or similar reference number Fine-print disclosures indicating the sender is not affiliated with First Bank Because the postcards mention First Bank and a mortgage loan, some recipients may mistakenly believe the communication came from the bank. How did the sender get my information? Mortgage information, including the existence of a mortgage and the lender’s name, is available through public land records. First Bank does not sell customer mortgage information to third parties for these mailings. In many cases, companies use publicly available property and mortgage records to identify homeowners and send marketing solicitations. Is this mailing from First Bank? No. First Bank does not use unaffiliated third-party companies to send mortgage postcards requesting that customers call unfamiliar phone numbers regarding urgent loan matters. If First Bank needs to contact you about your mortgage, communications will come through established First Bank channels. Should I call the number on the postcard? Customers should exercise caution before contacting unfamiliar companies that request personal or financial information. Before sharing any information, carefully review the mailing and verify the sender. If you are uncertain whether a communication is legitimate, contact First Bank directly using the phone number listed on our website, your mortgage statement, or other official bank communications. What should I do if I receive one of these postcards? If you receive a mortgage-related postcard that appears to reference First Bank: Review the mailing carefully, including any fine-print disclosures. Do not provide personal, account, or financial information to an unfamiliar party. Contact First Bank directly if you have questions about your mortgage or the legitimacy of a communication. Dispose of the postcard if you determine it is an unsolicited marketing piece. How can I verify a communication from First Bank? If you ever receive a phone call, email, text message, or mail piece that appears suspicious, contact First Bank directly using a trusted phone number or contact method before responding. Protecting our customers’ information remains a top priority, and we encourage customers to remain vigilant when receiving unexpected communications related to their financial accounts. Did you receive a suspicious mortgage postcard? Before calling any number listed on the mailing, contact First Bank directly using the customer support phone number on our official website to verify the communication. First Bank Customer Support Telephone: 1-866-792-4357 Hours: Mon – Fri: 7am – 8pm Saturday: 9am – 4pm Sunday: Closed   3 min read
Image for tile. Am I Eligible for FEMA Relief? Here’s What You Need to Know Who Qualifies for Assistance? Federal disaster aid is available for residents and business owners in the following counties: Alexander, Alleghany, Ashe, Avery, Buncombe, Burke, Caldwell, Catawba, Clay, Cleveland, Gaston, Haywood, Henderson, Jackson, Lincoln, Macon, Madison, McDowell, Mitchell, Polk, Rutherford, Transylvania, Watauga, Wilkes, and Yancey. Not sure if you’re eligible? You can verify your eligibility and apply directly on FEMA’s website: DisasterAssistance.gov. What Assistance Does FEMA Offer? FEMA provides a range of relief programs aimed at helping individuals and businesses recover from disasters. Here’s a closer look at what you may be eligible to receive: 1. Housing Assistance This aid helps you secure safe shelter while your home is being repaired or rebuilt. FEMA can provide funds for: Rental Assistance: Financial support to rent a temporary residence if your home is uninhabitable due to disaster-related damage. Lodging Expense Reimbursement: If you had to stay in a hotel or motel, FEMA can reimburse you for these expenses. This is especially helpful if you were unable to find immediate rental options. Home Repair or Replacement: Grants are available to help repair or replace your home and address disaster-specific damages, such as water damage or mold. FEMA may also cover hazard mitigation measures that reduce the risk of future damage. Accessibility Needs: If you or someone in your household has a disability, FEMA can provide funds to make your home accessible. This might include ramps, grab bars, and other necessary modifications, even if these were not originally present before the disaster. Privately-Owned Roads, Bridges, and Docks: If the only access to your home has been damaged, FEMA can help cover repair costs for private infrastructure like roads and bridges. 2. Other Needs Assistance This program helps with essential expenses and serious needs beyond housing. Covered expenses include: Serious Needs: Grants to cover immediate necessities like food, water, first aid, prescriptions, and personal hygiene items, ensuring you have access to essentials during recovery. Displacement: If your home is uninhabitable, FEMA can help cover the cost of staying with family, friends, or in a hotel while you search for a more permanent solution. Personal Property: Financial assistance to repair or replace items essential to daily life, such as appliances, furniture, and work or school-related items like computers and tools. This can also include uniforms, books, and equipment needed for self-employment. Medical and Dental Expenses: If the disaster caused injury or damaged medical or dental equipment, FEMA can help cover the costs for treatment, equipment replacement, and prescribed medications. Funeral Costs: In the unfortunate event that the disaster resulted in a loss of life, FEMA offers support to cover funeral or reburial expenses. Child Care: For families facing increased child care costs due to the disaster, FEMA can provide funds to help cover these additional expenses. Assistance for Miscellaneous Items: Reimbursement for items like generators, dehumidifiers, and chainsaws that were purchased or rented to aid in the recovery process. Transportation: If your vehicle was damaged and you don’t have an alternative mode of transportation, FEMA may help cover the repair or replacement costs to ensure you have a way to get to work, school, or other essential places. Moving and Storage Expenses: FEMA can help with costs associated with moving and storing personal property, especially if it needs to be relocated temporarily during home repairs or if you need to move to a new residence. Each of these programs is designed to provide immediate and practical support, so you can focus on the well-being of your family and community as you rebuild after the disaster. How Do I Apply for FEMA Assistance? Applying for FEMA relief is straightforward. Here are the steps to get started: Apply Online: Visit DisasterAssistance.gov to apply for assistance. You can also download the FEMA App or call FEMA’s toll-free number at 1-800-621-3362. Register for an Account: If you’re applying online, you’ll need to create an account on Login.gov. This will allow you to save your application, upload documents, and check your status. Prepare Your Information: You’ll need details like your home and mailing address, Social Security number, insurance info, and bank details for direct deposit. Submit Your Application: Once you’ve completed the application, review it, make any necessary changes, and submit it. Be sure to save your application ID as you’ll need it for future communication with FEMA. What Happens After You Apply? After applying, FEMA will review your application and may contact you for additional information or to schedule an inspection. You can always log into your account on DisasterAssistance.gov to check your application status and receive updates. If approved, FEMA will disburse funds via direct deposit or a mailed check, based on your preference. For more information or to begin the application process, visit DisasterAssistance.gov, call FEMA at 1-800-621-3362, or use the FEMA App. Recovering from Disaster with FEMA’s Support If you’re affected by Hurricane Helene, you don’t have to face it alone. FEMA offers a range of programs designed to help you get back on your feet. Take advantage of these resources to help ease the journey to recovery. 5 min read
What Are 20-Year Mortgage Rates? There are various factors to consider when purchasing a home, including how to finance it. Some consumers may opt for a mortgage with a shorter term while others find it beneficial to extend the mortgage. It may be best to look for a 20-year mortgage for a lower price without putting yourself in debt until retirement. First, let us help you answer the question, “What are 20-year mortgage rates?” What are 20-year Mortgage Rates? 20-year mortgage rates are an alternative to 15 and 30-year mortgage rates, the most common types of mortgage loans. 15, 20, and 30-year mortgages are usually offered as fixed-rate mortgages, meaning the interest rate you pay never changes. A 20-year fixed mortgage rate typically allows you to build equity faster and pay off your home in less time than other longer-term mortgage loans. They also typically have lower interest rates than other mortgage options because the term of the loan is shorter. Benefits of a Fixed-Rate Mortgage First Bank offers conventional fixed-rate mortgages, available in terms of 15, 20, and 30 years. There are many benefits to a First Bank fixed-rate mortgage, including: Predictable monthly P&I payments Protection from rising interest rates for the life of the loan Sound investment for long-term home owners What is an Adjustable Rate Mortgage? First Bank also offers adjustable rate mortgages, or ARMs. ARMs have interest rates that change periodically. When the rate changes, your monthly payment will either increase or decrease depending on whether the rates rise or fall. First Bank’s ARMs are available for 30-year amortization schedules, with initial periods of 3, 5, or 7 years. Contact First Bank Today Whether you’re buying a home or interested in refinancing, First Bank has a loan option for you. If you are still have questions about mortgage rates or conventional loans, contact the First Bank Mortgage Help Center, or visit a First Bank branch near you. 2 min read
Save Money with This Refinance Calculator for Home Mortgages When mortgage interest rates are low, homeowners should compare their current mortgage terms with the option of refinancing. By locking in the right rate, homeowners can take advantage of significant savings. Curious to see how much you could save with current rates? Use our refinance calculator for home mortgages to see how you can take advantage of major financial perks. Why Refinance Home Mortgages? Home mortgages are contracts. When the contract is signed, the interest rate selected by the homeowners is locked in until the terms of the contract have been satisfied or revised. The interest rates for home loans fluctuate daily. If interest rates are steadily dropping, homeowners can refinance to save money and improve their financial standing.   Benefits of Home Loan Refinancing Refinancing is a readjustment of your mortgage loan to benefit your finances in the following ways: Lower monthly payments Build home equity faster Improve credit Change to adjustable or fixed-rate plans When homeowners choose to refinance, they can generally expect to pay off their loan faster. 30-year mortgages can be refinanced to 12 or 10-year loans. Although it may sometimes increase the anticipated monthly payment, you can cash in on equity or sell for an increased value. When Is a Good Time to Refinance? When considering refinancing home mortgages, many homeowners weigh the closing costs with the savings achieved over time. It’s also important to think about the length of time you will live at the property. What to Do Next If You Want to Refinance After you’ve reviewed your savings on our refinance calculator for home mortgages, you may be interested in taking the next steps towards refinancing. Before making an appointment with your First Bank loan officer, make sure you have the following information updated: Current mortgage type Payment history Current credit report Outstanding debt Evidence of home renovations Evidence of home improvements/repairs Your loan officer will use this information to determine what kind of refinancing you may qualify for. There are plenty of options, and we can guide you in selecting the best package for your personal goals. Contact us today to apply for mortgage refinancing. *Loans are subject to credit approval ——— Sources: http://www.mortgagecalculator.org/helpful-advice/top-reasons-to-refinance.php http://www.mortgagecalculator.org/helpful-advice/top-reasons-to-refinance.php 2 min read
Mortgage Rates 101: Information You Should Know Acquiring information about mortgage rates is a vital step in the home buying process. Mortgage rates vary based on several factors, such as the amount and type of your loan and your credit score. To get better mortgage rates in your area, it’s best to contact your local lender like First Bank. First Bank’s Mortgage Center provides customers with answers to common questions about loan options, mortgage rates information, and more. Whether you are a first-time homebuyer, an experienced homebuyer, or building a new home, we provide information that can help you qualify for the loan and purchase your new home. Mortgage Rates Information from First Bank You will typically have multiple loan options to choose from before purchasing a home, including conventional mortgages, government loans, and construction loans. Two of the most popular types of home loans are conventional adjustable-rate and fixed-rate mortgages. Conventional adjustable-rate mortgages: Interest rate, monthly principal, and interest payments remain the same for an initial period of 3, 5, or 7 years, for example—then adjust periodically. Interest rate caps set a limit on how much your interest rate can increase. ARMs typically have a lower initial interest rate than fixed-rate mortgages. Monthly principal and interest payments may increase as the rate adjusts. Conventional fixed-rate mortgages: Interest rate and monthly payments stay the same for the duration of the loan. Offers protection from rising interest rates for life of the loan. Available in 15-year, 20-year, and 30-year fixed-rate loan term options. For more information on conventional mortgage rates or mortgage rates on our other home loan options, find your local First Bank loan officer today. Loans subject to credit approval. ——— Sources: Investopedia: http://www.investopedia.com/terms/c/credit_score.asp Investopedia: http://www.investopedia.com/articles/pf/05/022405.asp?lgl=mtdt-v1 2 min read
First Time Buyer? For most of us, buying a home is the largest purchase we’ll ever make. If you are a first-time homebuyer, you may be asking questions like, “What is a first home mortgage?” What is a First Home Mortgage? A first home mortgage is a loan you will use to purchase your first home. These loans can come in a variety of forms, from conventional home loans to FHA loans for first-time homebuyers. First Bank offers the following mortgage loans* for first-time homebuyers: Conventional Loans Government loans Professional loans Construction loans Jumbo loans In addition to providing a selection of mortgage opportunities, First Bank also offers a wealth of information about what a first home mortgage is and what can be expected when shopping for your first home. Tips for Buying Your First Home Knowing what a first home mortgage is can go a long way toward easing the process of turning that key for the very first time. U.S. News and World Report highlighted some of the most common mistakes first-time home buyers make and how you can avoid them. Among them were: Searching for your dream home before being pre-qualified for a loan. The reality of what a first home mortgage is can be vastly different than what you were hoping for. Take the time to seek out a mortgage loan specialist at a place like First Bank so you can find out what you can afford and what your expected monthly expenses will be. Thinking short-term. First-time buyers are often so focused on moving in that they don’t ever consider moving out. Chances are, you’ll one day be ready to move into another home as you start a family or change jobs. Think about the factors that will affect how you’ll be able to sell your home in five years such as economic growth in the area or neighborhood expansion. Making an emotional decision. It’s important to sign a mortgage paper with your head and not with your heart. You may be overlooking some serious red flags such as expensive repairs, structural damage, or mold simply because you’re in love with the open layout. Find a First Bank Near You Ready to get started? Check out First Bank’s guide 3 min read
Calculate Your Monthly Mortgage Loan Payment (with Taxes and Insurance) A mortgage loan calculator with taxes and insurance can help prospective homeowners prepare for the financial responsibility of owning a home. Purchasing a home may be one of the biggest decisions you ever make, so it is important to know how much your mortgage payment will be each month after taxes and insurance are added, so you can know how much house you can afford. How Much House Can I Afford? First Bank* provides a mortgage loan calculator with taxes and insurance for potential homebuyers who want to estimate their monthly payments before applying for a loan. Before you use the calculator, you will need to gather the following information: Loan term in years Purchase price Percentage down Interest rate Annual tax Annual insurance Once you have all of the necessary information, you can click here to calculate your potential monthly mortgage payment.** Applying for a Home Loan Now that you’ve calculated how much house you can afford, you may be ready to apply for a mortgage loan. You can get the homebuying process started by visiting First Bank’s online Mortgage Center. Our Mortgage Center provides you with tools, tips, and tricks to help you find a loan that meets all of your needs. Whether you are a first-time home buyer or ready to build your vacation home, we can structure a loan to meet your needs. First Bank offers a variety of home loan options*** with competitive interest rates, including : Conventional loans Government loans Professional loans Jumbo loans Construction loans Dream It, Own It loans The path to quickly finding an affordable home loan starts at First Bank. When you’re ready to apply, all you have to do is start an online application or visit your local branch to speak with one of  our home loan experts. *Member FDIC. Equal Housing Lender. NMLS #474504. **Determining exact rates and payments can be a complex process. Your exact rates and payment amounts will depend on a number of factors including geographical location and personal financial information. This tool provides you with an estimate of payments based on the information you put in but does not guarantee them. Loans are subject to credit and collateral approval. ***Loans subject to credit approval. 2 min read
Conventional Mortgage Loans Applying for a home loan can be a strenuous process, especially if you’re unsure which type of loan is the best fit for your financial situation. Before you apply, it is important to understand the two types of loans available to you: conventional mortgage loans and a government-backed loans. In this article, we’ll break down the basics of conventional loans. What are Conventional Mortgages? Conventional loans can have fixed or variable interest rates, which can be impacted by your credit score. Qualifications for conventional loans are usually stricter than government-backed loans because they carry a higher risk for banks and private lenders. If the borrower defaults on the loan, the banks and private lenders are not protected. These kinds of loans are not insured by the federal government, but they are still required to follow guidelines set by the Federal National Mortgage Association—a.k.a. Fannie Mae and Freddie Mac. A Conventional Loan to Meet Your Needs If you live in North Carolina or South Carolina and are looking for a flexible and affordable conventional loan,* look no further than your local First Bank. We offer both adjustable-rate and fixed-rate mortgages with a range of features and benefits that are sure to fit your specific financial needs. Conventional Adjustable-Rate Mortgages This kind of mortgage loan changes periodically depending on shifts in the corresponding financial index associated with the loan. ARMs generally have a lower initial interest rate than fixed-rate mortgages. Both your interest rate and your P&I (monthly principal and interest) payments will stay the same for an initial period of 3, 5 or 7 years. After that it will adjust periodically. Interest rate caps set a limit on how high your interest rate can go for your P&I payment for each adjustment and over the life of the loan. Loans are available for 30-year amortization schedules. Conventional Fixed-Rate Mortgages Your interest rate and P&I payments stay the same for the life of your loan. That predictability for your monthly P&I payments enables you to budget more easily. This kind of loan is available in a variety of loan term options, and it protects you from rising interest rates no matter how high they fluctuate. This option is good for individuals or 3 min read
Where to Get 15-Year Mortgage Rates If you’re ready to buy a home, you’re probably wondering where to get 15-year mortgage rates, or you may just be wondering what a mortgage is. First Bank will go over your options with you and help you determine what type of home loan is best, whether that be a 15-year mortgage, or a 3/3 adjustable rate mortgage. Types of Loans at First Bank Before we tell you how and where to get 15-year mortgage rates, we’ll go over some of First Bank’s mortgage options. We offer: Conventional loans Jumbo loans Government loans VA loans Construction loans Dream It, Own It If you are a first time home buyer, you’re probably looking for a conventional loan. We offer two types of conventional loans: fixed-rate and adjustable-rate. Adjustable-Rate Mortgages vs. Fixed-Rate Mortgages Conventional adjustable-rate mortgages (ARMs) have interest rates that will change periodically depending on shifts in a corresponding financial index that’s associated with the loan. This basically means that your rate will change, causing your monthly payment to increase or decrease. ARMs can be beneficial for some home buyers because they typically have lower initial interest rates than fixed-mortgages, and they provide homeowners flexibility. Conventional fixed-rate mortgages offer a more straightforward approach to home buying. With a fixed-rate mortgage, your monthly interest rate never changes, making it easier for you to set a monthly budget. A lot of people prefer fixed-rate mortgages because they offer protection from rising interest rates for the life of the loan. Secure a Mortgage with First Bank We hope you feel a little more prepared to take on a mortgage and buy the house of your dreams. If you’re ready to apply for a mortgage loan*, visit your local First Bank, or contact our mortgage loan experts. *Loans subject to credit approval. ———— Sources: Investopedia: http://www.investopedia.com/terms/a/arm.asp 2 min read
FHA Loans vs. Conventional Loans: How to Tell the Difference Overwhelmed with the prospect of buying a home? FHA loans and conventional loans are likely two sources of financing that you’ve considered. Let First Bank help you understand these options and come to a conclusion about which best suits your needs and budget. After all, choosing the right loan is key for timely, affordable payments. Choose the Right Loan with First Bank If you’re a first-time homebuyer or interested in purchasing your second home, there are different qualifications for each loan you should consider: FHA loans—The FHA, or Federal Housing Administration, provides mortgage insurance on loans made by approved lenders. Single and multi-family homes in the United States (and U.S. territories) can qualify. First Bank can help put you on the right track to securing one of these loans. The advantages of an FHA loan can be: Owing a lesser down payment, as low as 3.5%. Enjoying quicker eligibility following a major credit issue such as bankruptcy or foreclosure. Allowing a co-applicant to help you get the loan, even if you don’t live in the same household. Conventional Loans—A non-government insured loan that can be used with a second home purchase or an investment. Unlike FHA loans, conventional loans can require a higher credit score (often a minimum of 640), but they can have some major advantages for you. Conventional loans can allow: A risk-based premium, unlike FHA where one set premium rate is required from everybody, MI if applicable. Your monthly payments to be lower, even if you have a higher interest rate. Your loan to cover a higher loan amount. You to cover different types of loans like, investment or second home (FHA doesn’t do those types). When considering an FHA loan versus a conventional loan, keep in mind that conventional loans are not affiliated or insured with the government like FHA loans. Additionally, an FHA requires mortgage insurance and conventional loans do not, unless the LTV exceeds 80%. There is an upfront MI premium (1.75%) that is required on FHA loans that is not required on Conventional loans. For a more detailed look at FHA loans versus conventional loans, or assistance with applying, call or meet with your local mortgage loan professionals. *Loans subject to credit approval. 3 min read
Refinance Your Mortgage with These 5 Tips Over time, the mortgage market fluctuates and creates new opportunities for homeowners to revise the terms of their mortgage. This is known as refinancing. When refinanced, a mortgage can include lower interest rates, home equity credit, and a restructured loan duration. Homeowners will refinance for many reasons: to get a cash out, to buy out someone on the title, to consolidate their debt, for a low-rate bridge loan, and more. Test out this Refinance Mortgage Calculator, and then see if the following tips can save you time and money in your search for the perfect home loan. 5 Tips to Refinance Your Mortgage Lock in a Cost-Efficient Rate. Ultimately, it is a good idea to lower your monthly payment and re-structure the length of time it will take to pay off your loan. If you are purely looking for a lower rate, according to the Federal Reserve Board, the interest on the mortgage needs to be 1-2% lower than their current mortgage loan rate. Keep in mind that a lower rate isn’t always possible during a refinance, depending on your reason for doing the new loan. Evaluate the Terms. When it comes to mortgage refinancing, you should always read the fine print. Some lenders may offer lower rates, but with much longer terms. To determine if a loan is worthwhile compared to your current mortgage, multiply what you are currently paying (principle with interest, but not escrow) by the number of months left. Do the same for the refinance option and compare to determine if it is a good fit. Consider the Benefits of a New Type of Mortgage. If you are looking to refinance your mortgage, a great tip is to check out the variety of loan types lenders offer. Each may have advantages and disadvantages, and one may be a better fit for your situation. For example, if your financial assets have grown or changed, you may benefit from switching to an adjustable-rate mortgage (ARM) or a fixed-rate mortgage (FRM), depending on your unique needs. Don’t forget about property taxes and escrow accounts, which can also significantly impact your monthly payment amount. Shop Around. The financially savvy homeowner is aware of the many options available for mortgage refinancing. Ask a lot of questions. 3 min read
Five Reasons to Refinance Your Mortgage Banking professionals suggest mortgage refinancing when homeowners want to replace their current loan with a new one, often to reduce monthly payments or lower interest rates. With a mortgage refinance, your current loan is paid off and replaced with a new one. This can be a great option for borrowers with good credit who want to alter their current loan. But refinancing could be risky for borrowers with less than perfect credit. Check out our list of reasons to refinance and see if you could benefit from refinancing your current mortgage. 5 Reasons to Refinance Lower interest rates—If mortgage rates have dropped since you first took out your loan, you could secure a lower rate by refinancing. Lower monthly payment—Lowering your interest rate could have a dramatic impact on your monthly payment. If you intend on staying in your home for several years, lowering your payment could help you save. Shorten loan term—When interest rates fall, homeowners can often significantly shorten their loan term by refinancing without much increase in their monthly payment. Convert between adjustable-rate and fixed-rate—With adjustable-rate mortgages, your initial interest rate may be low and and then increase over a period of time. Refinancing to a fixed-rate mortgage could allow you to avoid an increase in rate. Cash out to make a large purchase—If you have equity in your home, refinancing enables you to cash out on that equity without taking out a loan, such as a home equity loan. A lot of people will use this cash to pay for home repairs, college tuition, or make a large purchase, such as a car. These types of refinances are typically easy to complete and may even be tax deductible. If you still aren’t sure if a mortgage refinance is right for you, visit our online refinance calculator to see how much you could save, or visit your local First Bank branch to speak with a mortgage specialist. Loans subject to credit approval. First Bank is not a student loan provider and does not offer or service student loans. ——— Sources: https://www.investopedia.com/mortgage/refinance/when-and-when-not-to-refinance-mortgage/ 2 min read
Get In Touch
First Bank has the resources you need, when you need them. Our personal banking services are there for you at the right time, every time.
First Bank logo
Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognizing you when you return to our website and helping our team to understand which sections of the website are the most popular and useful.